Assign Monthly Budget Record Checks in Your Household
Create an optional household checklist showing who will check each monthly budget item, which records they will use, and what remains unresolved.

To assign monthly budget record checks in your household, give each budget item a named checker, identify the statement, bill or receipt they should use, and leave space for their finding and any unanswered question. Keep this assignment sheet alongside your monthly budget. The optional workflow below concerns who checks the records; it does not assign responsibility for paying a bill or decide how household members divide costs.
Define the monthly checking task
Work and Income recommends making or revisiting a budget to consider whether it still meets your needs. [1]
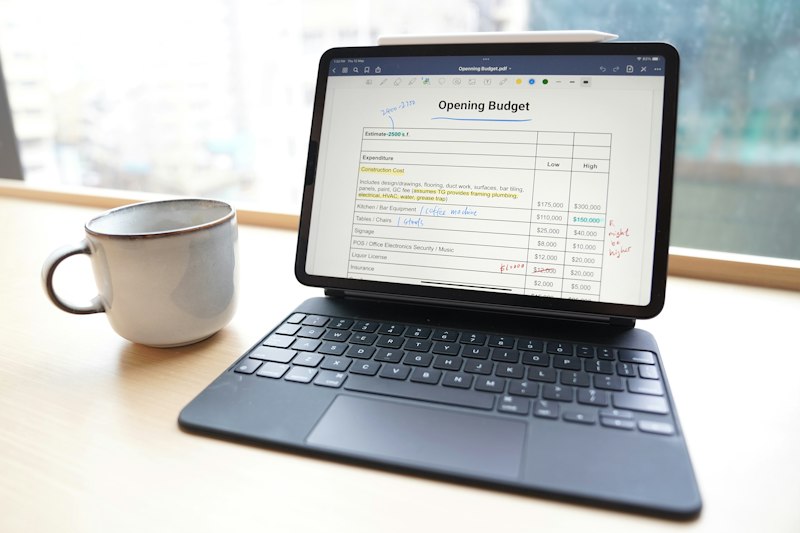
For your own recordkeeping, you could begin with the monthly budget you already use. Write its month at the top of a separate assignment sheet. Keep the same household scope and category names so that a checker can point to an existing budget item without creating a different version of it.
Choose a specific question for each assignment. For a planned cost, that might be whether the amount agrees with the bill currently held. For income, it might be whether the amount entered agrees with the relevant statement. Avoid broad assignments such as “check everything”, which leave the requested work undefined.
You could also name a budget coordinator: the person who receives findings and records agreed changes. If you keep the budget yourself, you can hold both roles. Write down the roles separately so the sheet still distinguishes checking a record from changing a budget entry.
Create a household assignment sheet
An optional starting layout is below. Use a row for each checking assignment, with a reference to the relevant budget item. These rows are administrative tasks, not additional expenses, and their contents should not be added to your cost total.
| Field | What you could enter |
|---|---|
| Budget item | The existing income or cost label |
| Checker | The person accepting the task |
| Record reference | A statement, bill, receipt or planned-cost note |
| Question and finding | What to check and what the record shows |
| Follow-up | Any unresolved point, next action and chosen reminder date |
Ask household members to choose assignments they can carry out using records available to them. You could write “awaiting assignment” where nobody has accepted a task. Keep the task visible instead of entering someone’s name without agreement.
For the record reference, use a description that points to the document: its filename, statement period or place in your paper folder. If the budget amount is a plan rather than a documented charge, identify the planning note and retain its estimated status. Do not present a checker’s agreement with an estimate as confirmation of an actual cost.
Keep payment responsibility outside this sheet unless you explicitly need a separate field for it. Someone may check a bill that another household member pays. Likewise, a person’s name beside a checking task should not change the household’s existing arrangement for sharing that cost.
Record findings and unresolved questions
You could ask each checker to return a short finding using the same format: the budget item, the record consulted, what it establishes and anything still unanswered. For example, a finding might state that the planned entry agrees with the bill held, while a question about which month it belongs to remains open. This is a suggested note format, not a conclusion about any particular bill.
Keep unresolved amounts and uncertain purchases on a separate pending list. Do not silently replace them with zero. If records are incomplete, label any sum of verified purchases as a provisional subtotal and describe what remains unresolved. Leave the related assignment open until the available evidence answers its question.
If a checker consults both a receipt and a matching bank entry, retain them as supporting records for the same purchase. Record that purchase total once. A verified receipt can establish a purchase even while its bank match remains unresolved; an unexplained bank entry should remain unresolved rather than receive an invented explanation.
For cash purchases, you could use a receipt or cash-spending log and identify cash in a payment-method field. Keep withdrawals separate from purchase spending: the withdrawal alone does not identify what was bought. Do not add both the withdrawal and the purchases funded by it to spending.
Read the monthly planning example
The example below illustrates monthly income minus monthly costs after those inputs have been selected. Use it to distinguish the budget calculation from the assignment sheet: checking tasks describe work on records, while the calculation uses financial amounts.
Hypothetical cash-flow example
These invented figures demonstrate arithmetic, not typical incomes or recommended spending amounts. Assume take-home income and all planned costs stay the same each month. Costs include essentials, required debt payments and other planned spending. Start with no money set aside for this example; assume no interest, fees, withdrawals or unexpected costs.
| Item | Amount |
|---|---|
| Monthly take-home income | NZ$5,400 |
| Total monthly planned costs | NZ$4,700 |
| Monthly amount left: 5400 minus 4700 | NZ$700 |
| Amount set aside after 6 months: 700 times 6 | NZ$4,200 |
This total is possible only if the full amount left is set aside each month under these assumptions. It is not a forecast. If income falls or costs rise, recalculate before choosing an amount to set aside.
A monthly planning surplus does not show the cash available today or before a bill is due. Check the current balance and the dates and amounts of expected income and payments before setting money aside; keep money needed for bills available.
The monthly difference is a planning surplus under the example’s stated assumptions. It is not a dated account balance. A balance for a particular date also needs the starting balance and the dates and amounts of income and payments. Keep those timing details separate from a checker’s statement that a monthly budget input agrees with its supporting record.
For your own worksheet, you could attach the assignment references to the relevant income and cost lines. Leave any uncertain input visibly marked rather than using the example’s fixed assumptions as evidence about your household.
Close or hand over each assignment
Choose a reminder date for outstanding tasks if that suits your household. At your chosen review, you could mark each assignment as checked, awaiting a record or awaiting a decision. Define “checked” narrowly: the requested comparison has been completed and its finding recorded. It need not mean that every question about the item has been resolved.
When a finding calls for a budget change, the coordinator could review the supporting record before entering it. Keep the checker’s finding beside the assignment, including unresolved qualifications. If another person takes over, record their name and the remaining question rather than treating reassignment as completion.
Govt.nz says bank statements, bills and details of money owed are useful documents to bring to a financial mentoring meeting. It also states that information shared in that meeting is confidential. [2]
If you arrange such a meeting, you could take your assignment sheet alongside those documents, with completed checks and unanswered questions marked separately. Treat the sheet as your own organisational aid, rather than something the source requires.
Frequently asked questions
Does the checker have to pay the bill?
In this optional worksheet, the checker examines records and returns a finding. You can keep payment responsibility in a separate field or your existing household arrangement; assigning a check does not change it.
What if nobody can access the supporting record?
Leave the assignment pending. Note which record is missing, who will try to obtain it and a reminder date if useful. Retain any uncertainty attached to the budget amount.
Should checked assignments be added to monthly costs?
No. The assignment sheet records administrative work. Use the financial entries in the budget for its arithmetic, counting each expense once; do not add task rows or supporting documents as further costs.
This article is general information, not personal financial advice.