Build a Calendar-Month Budget from Bank Statements
Organise statement entries into a calendar-month worksheet, note gaps in the records, and keep recorded income and costs separate from next month's planned amounts.

To build a calendar-month budget from bank statements, choose the month, list which dates each statement covers, and copy only that month's relevant entries into a worksheet. Keep missing records and uncertain entries visible. Then prepare your monthly planning amounts separately, so recorded spending and expected costs do not become mixed together.
Work and Income recommends revisiting an existing budget to check that it still serves your needs. [1]
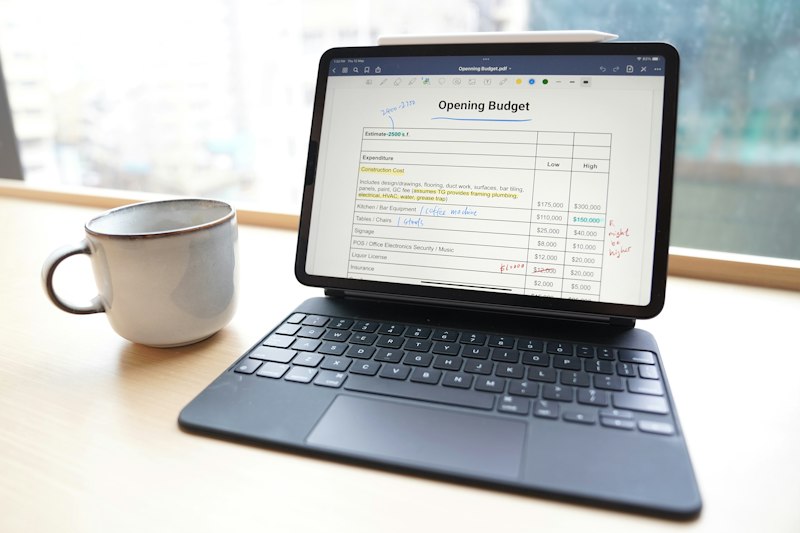
The worksheet below is an optional way to organise that review when your statements cover different periods. Its task is to assemble the records for a named month and document what still needs checking.
Choose the month and record convention
Start by writing the calendar month at the top of your worksheet. Add a short scope note naming the household accounts and records you intend to include. You might list your everyday account, another account used for bills, and a cash-spending log. Leave account numbers out of any copy that does not need them.
For this worksheet, you can choose the transaction date shown on each statement as the rule for assigning bank entries to a month. Write that convention beside the month label and apply it consistently. If a record shows several dates and you cannot tell which fits your convention, put it on the unresolved list before assigning it.
Give cash purchases their own date convention, such as the purchase date on the receipt or cash log. Keep this note with the worksheet rather than deciding differently for individual purchases. The aim is to make your chosen monthly boundary explicit.
List statement coverage and gaps
Create a coverage list before copying amounts. For each account, record the statement filename or paper reference, its covered dates, and whether you have checked the relevant part. If the month spans several statements, list each document separately.
You could use these headings:
| Record | Dates covered | Part needed for this month | Review note |
|---|---|---|---|
| Everyday account statement | Copy from document | Mark relevant dates | Checked or outstanding |
| Bills account statement | Copy from document | Mark relevant dates | Checked or outstanding |
| Cash-spending log | Copy from record | Mark relevant dates | Checked or outstanding |
Where documents overlap, mark which document you will use for the overlapping entries. Keep the other as a supporting record. Do not copy the same transaction again simply because it appears in another downloaded view.
Where coverage is missing, name the gap directly. For example, write that a statement covering part of the selected month is outstanding. Keep that note beside any subtotal prepared from the available records; do not label the subtotal as complete monthly spending.
Build the monthly entry worksheet
Use a separate entry sheet with columns for date, description, income or cost amount, payment method, source reference and review status. Copy descriptions from the records without inventing a purpose for an unfamiliar entry. Add a note if you need another document to understand it.
For purchases, use one row per transaction. A receipt and its matching bank entry are supporting records for the same purchase: enter the purchase total once and put both references on that row. Keep the question of whether the records match separate from whether you have evidence of the expense.
Include verified cash purchases once, using their receipts or cash-spending log, and mark the payment method as cash. Keep cash withdrawals outside purchase spending. A withdrawal alone does not identify what was bought, and counting both the withdrawal and the resulting purchases would count that spending twice.
You may also keep transfers between your own included accounts in a separate movement list. Do not treat both sides as household income and costs. If you cannot establish what an entry represents, leave its classification unresolved rather than forcing it into a spending row.
Keep supporting bills linked to the relevant entry. If you use a bill to propose a future planning amount, put that amount on the planning sheet described below, rather than adding it again to recorded spending.
Keep unresolved records visible
Maintain a short unresolved list with the record reference, the question, any known amount and the document you want to check. An unfamiliar bank entry should stay unresolved; do not explain it as a cash purchase or assume that identical entries establish duplicate charging.
A verified receipt can establish a purchase even while its bank match remains unresolved. In that case, include the supported purchase once and label the matching question separately. If the purchase itself or its amount is uncertain, retain it on the unresolved list rather than silently treating it as zero.
If a verified refund appears, retain the original purchase and link the adjustment to it. Under your stated monthly date rule, calculate recorded net purchase spending as purchase totals minus the verified refunded portions assigned to that month. Subtract each adjustment once. Leave a refund that has not been verified unresolved.
At the bottom of the worksheet, state what has been summed and what remains outstanding. If records are incomplete, call the result a provisional subtotal of verified purchases. Do not present it as complete actual monthly spending, even if every available document has been reviewed.
Prepare monthly planning amounts
On a separate sheet, list expected monthly income and planned monthly costs. Add a source note beside each amount, such as an existing bill, a statement entry or a household estimate. Keep uncertain or one-off income separately identified rather than presenting it as dependable monthly income.
If you choose to use an average for a cost that does not occur every month, label it as a monthly planning average and retain the underlying bill reference. Keep the actual due date separately. The average does not establish money available before that payment is due.
The hypothetical example below illustrates monthly income minus costs using fixed planning inputs. Its assumptions are part of the example; your assembled records do not establish that your own future amounts will follow that pattern.
Hypothetical cash-flow example
These invented figures demonstrate arithmetic, not typical incomes or recommended spending amounts. Assume take-home income and all planned costs stay the same each month. Costs include essentials, required debt payments and other planned spending. Start with no money set aside for this example; assume no interest, fees, withdrawals or unexpected costs.
| Item | Amount |
|---|---|
| Monthly take-home income | NZ$4,800 |
| Total monthly planned costs | NZ$4,250 |
| Monthly amount left: 4800 minus 4250 | NZ$550 |
| Amount set aside after 6 months: 550 times 6 | NZ$3,300 |
This total is possible only if the full amount left is set aside each month under these assumptions. It is not a forecast. If income falls or costs rise, recalculate before choosing an amount to set aside.
A monthly planning surplus does not show the cash available today or before a bill is due. Check the current balance and the dates and amounts of expected income and payments before setting money aside; keep money needed for bills available.
Read the difference as a planning surplus. It is not a dated account balance. To work out a balance on a particular date, you would also need the starting balance and the dates and amounts of income and payments.
If you take your worksheet to a financial mentor, Govt.nz says bank statements, bills and details of money owed are useful documents to bring. [2]
Frequently asked questions
What if a statement crosses the month boundary?
Keep it in the coverage list and select entries using your written date convention. Retain the full statement as a supporting record, while limiting this worksheet to the selected month.
Can I finish while a statement is missing?
You can prepare a provisional worksheet. Name the missing coverage and keep unresolved amounts visible. Leave the complete monthly spending total unfinished until the relevant records are accounted for.
Should next month's plan equal this month's recorded costs?
Keep them as separate fields. You may use the records as inputs, then label each planned amount and its basis. Do not silently replace a recorded amount with an estimate or present an estimate as verified spending.
This article is general information, not personal financial advice.