Record Your Share of Shared Bills in a Monthly Budget
Use existing bills and agreed household contributions to record your share of shared costs, then carry that amount into your personal monthly budget.

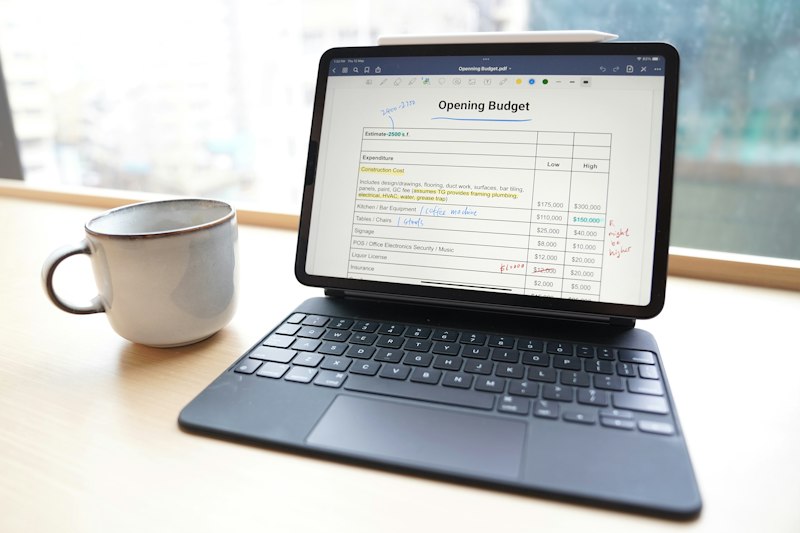
To record your share of shared bills in a monthly budget, list each existing bill once, note the contribution you have agreed to pay, and carry only your share into your personal cost total. Keep the full household bill beside it for reference. The worksheet below is an optional way to organise those amounts when you share costs with flatmates, a partner or whānau.
A budget can support you in directing your money and deciding how to use it. The New Zealand Government describes this as a way to maintain control over your finances. [1]
Define whose monthly budget you are preparing
Start by writing the month and whose income and costs the plan covers. For this worksheet, use a personal budget: your income, your personal costs and your agreed shares of household costs. If you normally budget jointly, you could instead prepare the worksheet for everyone included in that joint plan. Keep that boundary consistent throughout.
Add a short scope note beside the month. For example, describe which household members are included and whether the sheet covers shared rent, shared services or other agreed household bills. Leave personal purchases outside the shared-cost sheet and include them separately in the personal budget.
You could also note who is responsible for making each payment. Keep that responsibility separate from the agreed cost share. Someone paying a full bill on behalf of the household needs a different payment record from someone paying only their own contribution. This worksheet will describe the planned allocation; keep records of money actually paid alongside it.
List the shared bills for the month
Gather the existing bills, statements and any written record of agreed contributions that relate to the planning month. Use the amount shown on a bill where it is available. If you are planning before the bill arrives, label the amount as planned and note the record you used as its basis.
An optional worksheet could use these columns:
| Field | What to enter |
|---|---|
| Cost description | The shared bill or agreed household cost |
| Reference | The bill, statement or agreement used |
| Planning month | The month receiving the planned allocation |
| Full cost | The amount being divided |
| Your share | Your agreed contribution |
| Other shares | The combined contributions allocated to others |
| Amount status | Documented, planned or unresolved |
| Payment responsibility | Who is expected to make the payment |
Choose a month rule and write it above the table. One option is to assign a cost to the month in which you expect to pay your contribution. Apply that rule consistently rather than moving a cost between months to change the total. Keep the bill’s service period in the reference notes if it differs from the planning month.
Where a planned amount is uncertain, retain that uncertainty in the status field. You could list an agreed provisional amount and explain its basis. If no amount has been agreed, leave the allocation unresolved and describe what information is missing. Do not silently enter zero for an unknown cost.
Record the agreed share of each cost
Enter the full bill once, then record your agreed share and the combined shares assigned to everyone else. Use the household’s existing arrangement; the worksheet does not prescribe equal contributions or any other division. If the arrangement is unclear, mark the share as unresolved until the people involved agree it.
As a simple arithmetic check, add your share to the other allocated shares and compare the result with the full cost. If they differ, record the unallocated amount or the excess allocation in a note. Check the source record and the agreed split before changing an entry.
When transferring figures to your personal budget, use the personal-share column. Keep the full-cost column as a reference rather than adding both columns to expenses. Under this worksheet convention, the full bill describes the shared cost, while your share describes the amount allocated to your personal plan.
If you expect to pay the full bill and receive contributions from others, keep a separate payment note showing the outgoing payment and expected contributions. Do not label those contributions as extra earnings in this personal-share worksheet. Mark any uncertain contribution explicitly and review how it affects the payment plan.
Carry your shares into the monthly plan
Add the resolved personal shares for the month and carry that subtotal into your personal budget. Then include your other planned costs. If any shared costs remain unresolved, label the combined cost total as provisional and list the missing allocations beside it.
The hypothetical example below subtracts total monthly planned costs from monthly take-home income. It does not separately show shared bills or their allocation.
Hypothetical cash-flow example
These invented figures demonstrate arithmetic, not typical incomes or recommended spending amounts. Assume take-home income and all planned costs stay the same each month. Costs include essentials, required debt payments and other planned spending. Start with no money set aside for this example; assume no interest, fees, withdrawals or unexpected costs.
| Item | Amount |
|---|---|
| Monthly take-home income | NZ$4,200 |
| Total monthly planned costs | NZ$3,600 |
| Monthly amount left: 4200 minus 3600 | NZ$600 |
| Amount set aside after 6 months: 600 times 6 | NZ$3,600 |
This total is possible only if the full amount left is set aside each month under these assumptions. It is not a forecast. If income falls or costs rise, recalculate before choosing an amount to set aside.
A monthly planning surplus does not show the cash available today or before a bill is due. Check the current balance and the dates and amounts of expected income and payments before setting money aside; keep money needed for bills available.
Read the difference as a planning surplus under the example’s stated assumptions. It is not a bank balance or evidence that money will be available on a particular payment date. A dated balance also needs the opening balance and the dates and amounts of incoming money and payments.
For an optional timing note, record when your contributions are due and when you expect income. If you pay a full bill before others contribute, record that sequence too. Review the current balance, existing commitments and payment dates before treating a monthly planning surplus as money available to move elsewhere.
Update the allocation when arrangements change
Work and Income recommends revisiting an existing budget to check whether it is still serving its purpose. [2]
You could choose a monthly review point to compare the allocation sheet with the bills now available. Replace a planned amount with the documented amount when appropriate, retain a note of the change and recalculate the affected share. Keep a new split attached to the month in which the household agreed it would apply.
Work and Income also says a budget should reflect changes in income or costs affecting you and your whānau. [2]
If someone joins or leaves the household, you could check each shared-cost row against the revised arrangement. Record who agreed the new contribution and which month it starts. Leave earlier months as recorded unless you are correcting an identified recordkeeping error.
Frequently asked questions
Should I put the whole bill in my personal budget?
For the personal-share method described here, carry your agreed share into planned costs. Retain the whole bill on the allocation sheet. If you pay the full amount yourself, keep that payment and the associated contributions in the separate payment record.
What if a bill or contribution is still unknown?
Keep it on an unresolved list with the missing information stated. Label the available cost subtotal as provisional. You could add a reminder to check the bill or confirm the agreement before treating the monthly plan as settled.
Does a smaller share mean I have money available to save?
Review the whole personal budget before making that decision. A change to one allocation alone does not establish a household surplus. Check the remaining costs, unresolved amounts, existing commitments, current balance and payment dates as well.
This article is general information, not personal financial advice.