Label Estimates and Verified Costs in a Monthly Budget
Use existing statements, bills and planned costs to label the evidence behind each monthly budget amount, with a separate list of questions to resolve.

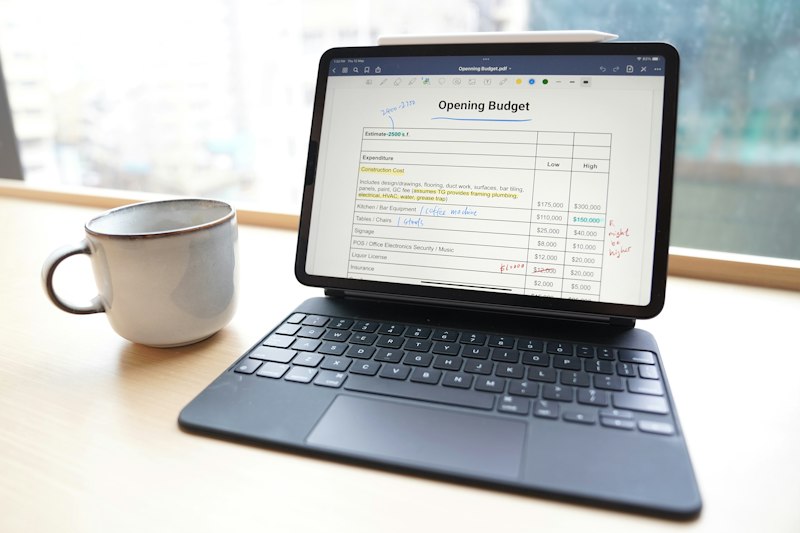
To distinguish estimates from verified costs in your monthly household budget, add an evidence status beside each planned amount and name the statement, bill or receipt supporting it. Keep unanswered questions in a separate list. The result is an annotated monthly plan: it shows which figures have supporting records and which still need checking, without treating missing information as zero spending.
Govt.nz describes budgeting as a way to exercise more control over your money and how you use it. [1]
The worksheet below is an optional recordkeeping method. Use it with an existing budget rather than creating another set of expenses to add to that budget.
Set up a monthly evidence worksheet
Choose a calendar month and write it at the top of your worksheet. You could keep the worksheet beside your existing budget, or add the suggested fields directly to it. Label the main amount column “planned monthly cost” so its purpose remains clear throughout the review.
For each existing cost line, you could add an evidence status, a supporting-record reference and a next action. Keep the original category name and planned amount visible. If your budget includes a monthly provision for a less frequent bill, retain that planning basis and label it as a provision; the full bill amount belongs in the supporting information, not automatically in that month's planned-cost total.
Define each cost line before attaching records. For example, decide whether a food category covers food alone or also includes household supplies. Keep that definition beside the planned amount, and use the same scope when selecting supporting information. Avoid treating a mixed shopping receipt as evidence of food spending alone.
You could also record when you prepared the worksheet. Treat this as the date you reviewed the records, not proof that every cost for the month has been accounted for.
Give each planned cost an evidence status
Choose a small set of labels and write their meanings on the worksheet. The following labels describe the evidence behind the planned amount; they do not declare the whole month's actual spending complete.
| Status | Suggested meaning | Optional next action |
|---|---|---|
| Estimate | The planned amount has no supporting record attached | Note how you chose it and what to check |
| Historical record | A previous statement or bill supports the planning basis | Record the period covered |
| Relevant record checked | You checked an applicable record and noted its scope | Keep its reference beside the amount |
| Unresolved | The amount, coverage or relationship between records needs checking | Write a specific question |
Use “verified” narrowly if you prefer that word: record exactly what you verified. Checking a figure against an earlier bill verifies the transcription from that bill. It does not establish that the same cost will apply in the month you are planning.
Keep the planned amount and the evidence status separate. If an estimate remains your chosen planning figure, leave it visible as an estimate. Do not replace it with zero because a record is missing, or silently substitute an older amount without identifying its period.
Keep supporting records separate from budget totals
You could use a short reference such as the record's name, statement period or receipt date. Keep any copied amount in a clearly labelled supporting-information field. Sum only the planned monthly cost column when calculating the household plan; do not add the supporting-record amounts as extra costs.
Where a bill, receipt and bank entry relate to the same purchase or payment, link them to the relevant cost line. They are supporting records of that expense, rather than separate expenses to add together. If you maintain a purchase list alongside this worksheet, use one row per purchase and record its total once.
For a mixed receipt, you could keep category allocations in a separate breakdown. Those allocations must add back to the single purchase total. Use only the relevant allocation when assessing evidence for a category with a narrower definition than the whole receipt.
For cash spending, use a receipt or cash-spending log and identify cash as the payment method. Keep cash withdrawals separate from purchase spending: a withdrawal alone does not identify what was bought. Adding both a withdrawal and the purchases made with that cash would count that spending twice.
Keep evidence of an expense separate from the matching status of its records. A verified receipt can establish a purchase while its bank match remains unresolved. An unfamiliar bank entry should remain an unresolved entry until checked; do not label it a cash purchase or invent a reason for it.
Read the monthly planning example
Once your worksheet contains the planned household income and costs, you can use monthly income minus monthly costs to describe the planning surplus. Retain the evidence labels beside your own figures so the calculation does not hide which inputs are estimates.
Hypothetical cash-flow example
These invented figures demonstrate arithmetic, not typical incomes or recommended spending amounts. Assume take-home income and all planned costs stay the same each month. Costs include essentials, required debt payments and other planned spending. Start with no money set aside for this example; assume no interest, fees, withdrawals or unexpected costs.
| Item | Amount |
|---|---|
| Monthly take-home income | NZ$4,800 |
| Total monthly planned costs | NZ$4,350 |
| Monthly amount left: 4800 minus 4350 | NZ$450 |
| Amount set aside after 6 months: 450 times 6 | NZ$2,700 |
This total is possible only if the full amount left is set aside each month under these assumptions. It is not a forecast. If income falls or costs rise, recalculate before choosing an amount to set aside.
A monthly planning surplus does not show the cash available today or before a bill is due. Check the current balance and the dates and amounts of expected income and payments before setting money aside; keep money needed for bills available.
The example illustrates the arithmetic under its stated assumptions. Its accumulated amount assumes that every month's surplus is set aside. It does not show that your own estimated costs will occur, or that money will be available on a particular payment date.
A dated balance needs the starting balance and the dates and amounts of income and payments. A monthly planning average, including a provision for a less frequent bill, does not establish money available before that bill is due.
Review unresolved questions before closing the worksheet
For each unresolved line, you could write a question specific enough to revisit: which period does this bill cover, which category includes this purchase, or which record supports the amount entered? Add a reminder of your choice if another record is needed. Leave the question open until you have checked the relevant information.
If you also total verified purchases, label the result a provisional subtotal when records are incomplete. Keep uncertain purchases or amounts on the unresolved list rather than treating them as absent. Do not present that subtotal as complete actual monthly spending or use it to declare a final category variance.
Work and Income says a budget should reflect changes to household income and costs, and that changed circumstances can also call for reconsidering goals. [2]
As an optional closing step, update any planning figures you have chosen to revise, retain their evidence references and mark the remaining questions. Choose a monthly review point that suits your recordkeeping. Keep unresolved items visible in the next worksheet rather than marking them resolved simply because the month has ended.
Frequently asked questions
Can I use an older bill as evidence?
Yes, as an optional historical reference. Label its period and explain its relationship to the planned amount. Do not describe it as confirmation of a future bill or of spending in a different month.
Should every line have the same status before I use the budget?
You can retain a mixture of documented amounts and estimates in a planning worksheet. Keep those distinctions visible and state what remains unresolved. The monthly calculation uses the amounts entered; it does not verify their supporting evidence.
Does a lower documented cost mean I can save the difference?
A difference on one cost line does not establish a household surplus. Check the whole household budget, existing commitments, current balance and payment dates before treating an amount as available to spend or save.
This article is general information, not personal financial advice.