Organise Moving Costs in Your First Monthly Budget
Use existing bills and planned costs to organise the first monthly household budget after a move, separating ongoing expenses, moving costs and unknown amounts.

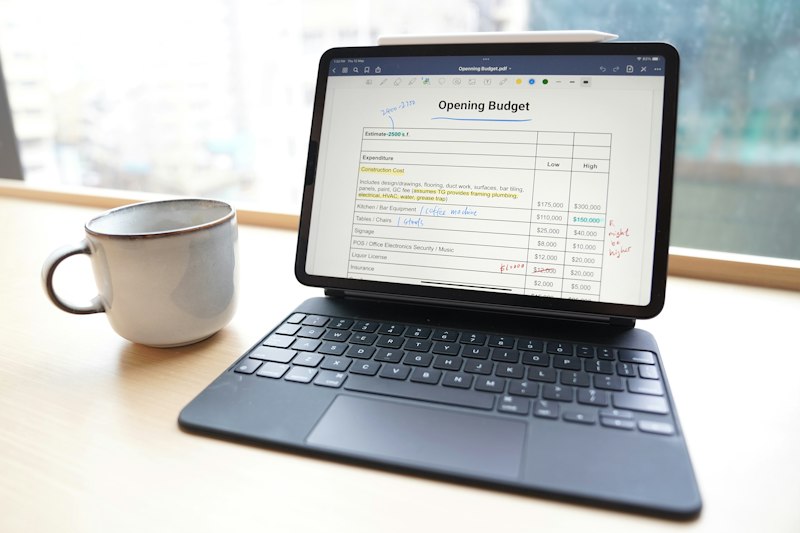
To organise your first monthly budget after moving house, choose a calendar month and create a worksheet with separate sections for ongoing household costs, one-off moving expenses and amounts still awaiting confirmation. Use existing bills, statements and documented planned costs as inputs. Keep a record of what each amount represents before subtracting the month's planned costs from its planned income.
Work and Income explains that a budget needs updating when circumstances change. Its examples include moving to a home with different costs and taking on part-time work that changes income. [1]
The worksheet below is an optional way to organise those changes. Its purpose is to record which costs you have included in the selected month and which figures still need checking.
Choose the monthly planning period
Write the month at the top of the worksheet. For this task, you could use the first calendar month after your move. If you also want to organise the month containing the move itself, give that month a separate sheet rather than combining parts of different months.
Choose and write down a consistent rule for assigning costs. For example, you could place each planned payment in the month when you expect to pay it. Keep the service or purchase period in a separate note. Apply your chosen rule throughout the worksheet, including to costs connected with your previous home.
Next, gather the records you want to use: existing household bills, relevant statement entries and documents showing planned moving expenses. Put records from the previous home and the new home in separate folders or piles while you work. Leave a place for documents you are still waiting for.
Assign each cost to one worksheet row
You could use the following columns for both ongoing costs and one-off moving expenses. Keep the two groups in separate sections of the same monthly worksheet.
| Field | What to enter |
|---|---|
| Cost description | The particular payment or expense being planned |
| Home or purpose | Previous home, new home or moving expense |
| Supporting record | Bill, statement entry or planning document |
| Planned monthly amount | The amount assigned to this month |
| Status | Documented, estimated or unresolved |
| Timing note | Expected payment date and relevant coverage period |
For ongoing costs, enter the amount relevant to your selected month. If you use an old bill as a planning reference, label the new entry as an estimate unless you have a record establishing the new amount. Keep the old bill's period visible rather than presenting it as a bill for the new home.
For one-off moving expenses, add a description specific enough to distinguish the cost from your ongoing household spending. You might choose labels such as removal service or packing materials where those costs appear in your records. Assign each to the month required by your chosen rule.
If a bill and a bank entry relate to the same paid cost, you could reference both on a single row and enter the cost once. When the relationship between records is unclear, mark it for checking before changing the total. Avoid treating similar descriptions as proof that two records concern the same expense.
Keep uncertain amounts visible
Create an unresolved list beneath the cost sections. For each missing or uncertain amount, record what you need to check, which month it might affect and the document you are looking for. You could add a reminder to revisit the entry when that record becomes available.
Keep an estimated amount distinct from an unknown amount. If you have chosen an estimate based on an existing record, show the amount and its basis. If you have no amount to enter, write “unresolved” rather than silently counting it as zero.
When adding the worksheet, label the result according to what it contains. A total including estimates is a planned cost total with estimates. If relevant costs remain unquantified, label the sum as a provisional subtotal and name the missing items beside it. Do not present that subtotal as complete monthly spending.
You could use the same approach for income: identify the amount you are using and flag anything uncertain separately. Keep one-off or uncertain receipts outside the dependable income figure rather than assuming they will recur.
Calculate the monthly planning result
Once you have entered the month's planned income and costs, subtract total planned costs from planned income. Keep one-off moving expenses within that month's cost total if your assignment rule places them there. Do not add a section subtotal again after already including its individual rows.
The hypothetical example below illustrates monthly income minus costs under fixed assumptions. It is separate from your moving worksheet: its figures do not estimate your relocation expenses or establish what your household will spend.
Hypothetical cash-flow example
These invented figures demonstrate arithmetic, not typical incomes or recommended spending amounts. Assume take-home income and all planned costs stay the same each month. Costs include essentials, required debt payments and other planned spending. Start with no money set aside for this example; assume no interest, fees, withdrawals or unexpected costs.
| Item | Amount |
|---|---|
| Monthly take-home income | NZ$5,600 |
| Total monthly planned costs | NZ$4,900 |
| Monthly amount left: 5600 minus 4900 | NZ$700 |
| Amount set aside after 3 months: 700 times 3 | NZ$2,100 |
This total is possible only if the full amount left is set aside each month under these assumptions. It is not a forecast. If income falls or costs rise, recalculate before choosing an amount to set aside.
A monthly planning surplus does not show the cash available today or before a bill is due. Check the current balance and the dates and amounts of expected income and payments before setting money aside; keep money needed for bills available.
The difference is a planning surplus. It does not establish the money available on a particular date. A dated balance also requires the starting balance and the dates and amounts of income and payments. Keep any timing notes separate from the monthly subtraction.
If your worksheet still contains unknown costs, retain the provisional label on its result. List those unresolved amounts alongside it rather than treating the apparent difference as an amount ready to set aside.
Prepare the following month's worksheet
For the next calendar month, you could copy the worksheet headings and review each row individually. Carry an ongoing cost forward only with an appropriate amount and status for that month. Leave a moving expense behind unless a separate payment belongs in the next period under your rule.
If you choose to use a monthly average for a less frequent bill, label it as a planning average and retain the actual payment timing separately. The average does not establish that money is available before the bill is due. Avoid counting both the average and the full bill as separate costs in the same planning total.
Government guidance says financial mentoring appointments are supported by records of account activity, household bills and outstanding debts. It also states that information disclosed during the appointment is confidential. [2]
If you choose to take this worksheet to an appointment, you could attach the supporting records and put the unresolved list first. Keep your own labels for estimates and unknown amounts visible.
Frequently asked questions
Can I use bills from my previous home?
You could retain them as references for planning estimates. Label the estimate and its source clearly, and replace it when you obtain the relevant new record. Do not relabel the old bill as an actual cost for your new home.
What if a cost concerns both homes?
You could keep one row for the cost and describe both homes in its purpose field. If you choose to divide it into allocations, keep those allocations separate from the single total and check that they sum to that total.
Should I wait until every amount is confirmed?
You can begin organising the worksheet with the records you have. Keep estimates labelled, retain unknown costs on the unresolved list and describe any incomplete sum as provisional. Update the entries when you have supporting information.
This article is general information, not personal financial advice.